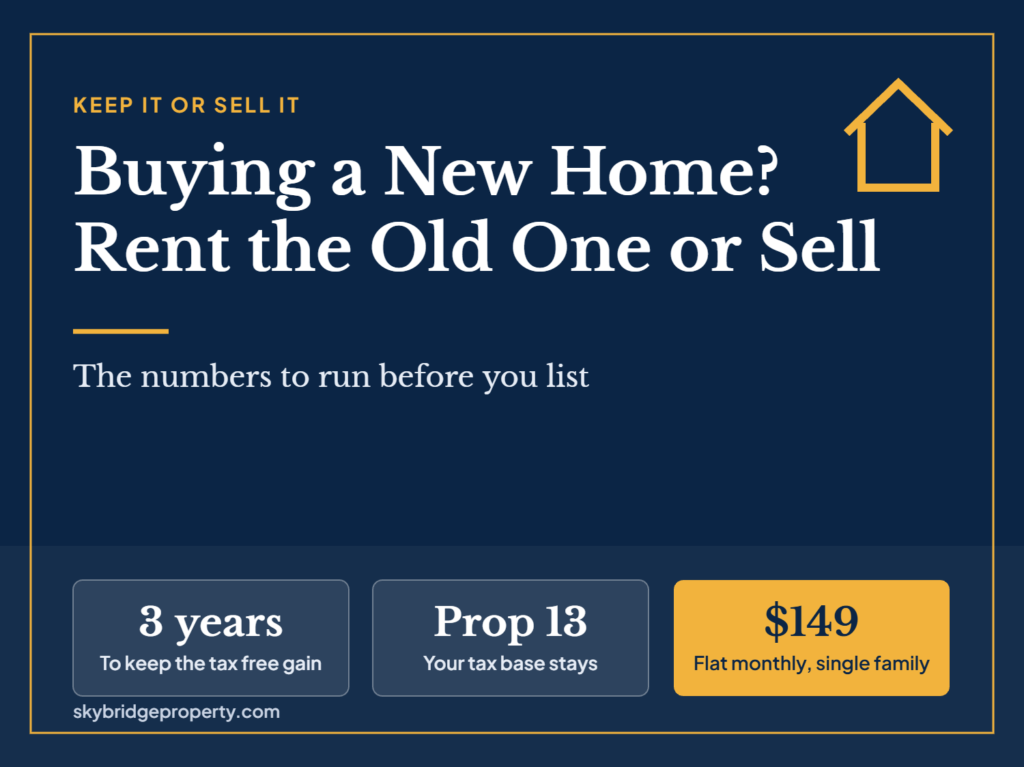
Keeping your current home as a rental makes sense when the rent covers your mortgage, property tax, insurance, HOA and a repair reserve with money left over, and when you are comfortable owning it for years. Selling makes more sense when the rent falls short or you need the equity for the next purchase. One deadline matters most: if you lived in the home two of the last five years, you can generally sell within about three years of moving out and still exclude up to $250,000 of gain ($500,000 for married couples).
This is one of the most common calls we get: an owner is buying a bigger home, moving closer to work or family, or upgrading, and wonders whether the current house should be sold or kept. Here is how we walk owners in Los Angeles and Orange County through it.
Step 1: Get a real rent number
Everything starts with what the home will actually rent for, not what a neighbor says. We build a rent comparable report from MLS data and rental listing software, because pricing decides both how fast a home rents and who rents it. Homes we price correctly typically lease in 7 to 21 days. Here is how we price a rental.
Step 2: Do the monthly math honestly
| Monthly item | What to include |
|---|---|
| Mortgage | Principal and interest on your current loan |
| Property tax | Your current bill. You keep your Prop 13 base, but you lose the homeowners’ exemption once it is a rental |
| Insurance | A landlord policy, which replaces your homeowner policy |
| HOA dues | If the home is in an association |
| Repairs and turnover | A monthly reserve for repairs, paint and vacancy between tenants |
| Management | $149 per month for a single family home at Skybridge, or $99 for a condo or townhome |
If rent minus all of that is positive, keeping the home can build long term wealth, especially with a low interest rate you could never get again. If it is negative every month, you are paying to hold the house, and selling usually wins unless you are confident in appreciation.
Step 3: Watch the capital gains clock
Federal tax law lets you exclude up to $250,000 of gain ($500,000 for married couples filing jointly) when you sell a home you lived in for at least two of the five years before the sale. Once you move out, that clock is running. Renting for a year or two and then selling can still qualify. Renting for four or five years usually does not, and the gain becomes taxable, along with depreciation you took as a landlord. Map out your timeline with your CPA before you decide.
Step 4: Check how it affects your new loan
If you are buying with a new mortgage, your lender decides how much of the expected rent counts toward qualifying. Many lenders count only part of the rent, and some want a signed lease first. Ask your loan officer before you list the old home for rent. Also check your current loan documents and HOA rules for any limits on renting.
Step 5: Decide whether you want to be a landlord
Renting a home is a business. It means screening, repairs, rent collection, notices and California’s rent rules. Single family homes owned by individuals are usually exempt from the AB 1482 rent cap if the lease includes the required notice, but local rules in some cities still apply. If you would rather not take the calls, a manager runs it for you. Our tenants are screened for a 720 credit score, income of 2.5 times the rent, and no prior evictions, and we have had one eviction in the last eight years.
When keeping it usually wins
- The rent covers every cost with room to spare.
- You have a low interest rate locked in.
- You do not need the equity for your next purchase.
- The home is in good condition and in an area with strong rental demand.
When selling usually wins
- The rent does not cover your costs.
- You need the equity for the new home.
- The home needs major repairs before it could rent well.
- You are close to the end of the three year window and have a large gain.
Frequently asked questions
Is it better to rent out my house or sell it when I buy a new one?
Keep it when the rent covers your mortgage, tax, insurance, HOA and a repair reserve with money left over and you do not need the equity. Sell when the rent falls short, you need the cash, or a large gain would become taxable because you rented too long.
How long can I rent out my house and still avoid capital gains tax?
Generally, you need to have lived in the home for two of the five years before you sell. That usually means selling within about three years of moving out. Confirm your dates with a CPA.
Will my property tax go up if I rent out my house?
Your Prop 13 assessed value stays the same because ownership does not change. You do lose the homeowners’ exemption, which raises the bill slightly.
What will my house rent for?
It depends on the location, size, condition and current comparable rentals. We will run a free rent estimate using MLS and rental listing data.
How much does it cost to have my old home managed?
At Skybridge, $149 per month for a single family home or $99 for a condo or townhome, plus 50% of the first month’s rent when we place a tenant. There is no onboarding fee, and you can cancel with 30 days notice.
Get your rent number before you decide
Call (909) 610-9780 and we will give you a free rent estimate, so you can compare keeping the home with selling it. When you call, a real person picks up.
General information, not legal, tax or lending advice. Talk with a CPA and your loan officer about your situation. Figures are current as of November 2026.